Article
·
time
-min
read
·
August 29, 2022
The Client Service Trifecta: Family Office Software Client Support, Education, and Training
Explains why client support, education, and training should be evaluated alongside functionality when selecting family office software.

Natalie Peters
·
Relationship Manager
Topics
Software
Operations
Industry
Categories
Family Office Software
Technology Due Diligence
Client Service
Using Client Service as a Mechanism to Qualify Family Office Technology Providers
Capabilities and tools, code and databases, reports and more reports.
When it comes to family office technology evaluations, these tend to be the topics that dominate most conversations. And for good reason: These topics are, no doubt, core to selecting a solution that will work for your family office.
But a technology solution that merely works for your family office is a far cry from a technology solution that enhances your family office. Your family office software should extend beyond functionality and reporting. Ideally, an investment of this magnitude should support the growth and strategy of the family, generation over generation.
In our experience, the key to finding a dependable technology partner with a staying power equal to the family wealth itself is to look beyond the product or service and evaluate the whole of the firm’s client service approach.
It’s no secret that at Archway Family Office Services, we routinely cite the importance of client service as a key consideration when choosing a family office software provider.
Client Support
Oftentimes, the most common face of client service is client support. In the traditional sense of client support, this is the real human answering the phone, replying to your email, or triaging your support ticket. In a more modern sense, it could equate to chatbots, automated voice systems, or robotic process automation (RPA).
When evaluating your technology provider’s client support capabilities, consider the following:
- Support hours and availability
- Location of support staff
- Types of support channels (i.e. phone, email, online support portal, etc.)
- Experience and/or qualifications of support staff
- Self-service support capabilities
Client Education
Client education can come in a variety of forms, from knowledge bases, setup guides, and product release notes to step-by-step process and policy documentation. A key pillar in any client service model, education is fundamental to giving clients the tools they need to successfully operate a wealthtech solution.
But perhaps more notably, this facet of client service puts clients in the driver’s seat, allowing them to acquire the knowledge and skills they need so that they can become self-sufficient within the application.
When evaluating your technology provider’s client education capabilities, consider the following:
- Availability of online, self-service product documentation
- Communication strategy related to product enhancements, upgrades, and announcements
- Creation of thorough process documentation and/or best practices for critical operations
- Access to how-to guides, tutorials, and setup manuals
- Opportunity to join peer networks and/or forums for best practices, tips, and tricks
Client Training
Ongoing client training is critical to maximizing your family office’s technology investment. Training represents the tipping point from becoming self-sufficient to proficient in an application and often covers more advanced features and functions of the technology.
At Archway Family Office Services, we offer a variety of training opportunities including ad hoc client-specific trainings, recorded tutorials, live group trainings, and our pinnacle training event exclusively for our family office clients: Archway’s IMMERSION User Conference.
When evaluating your technology provider’s client training capabilities, consider the following:
- Availability of dedicated, in-house training staff
- In-person and/or virtual group training opportunities
- One-on-one custom training opportunities
- Access to user conferences, regional user groups, or client communities
- Accreditation of training content
By checking the boxes in these three areas of client service, your family office can feel more confident in not only the technology you’ve selected, but the people, processes, and documentation that will support you going forward. More importantly, these areas—even more so than the software itself—will define how you engage, connect, and grow with your technology partner for years to come.
Learn more about how Archway Family Office Services builds lasting relationships and connects with our family office and financial institution clients through education, support, and training in our mini ebook, Our Commitment to Exceptional Client Service.
Related reading


Article
·
Single Family Offices
·
time
-min
read
Family Office Bill Pay: The Complexity Behind Cash and Expense Management
Learn how family offices can strengthen bill pay, cash management, fraud prevention, reporting, and operational control with a modern workflow.

Megan Greer
While family offices perform a myriad of functions, their primary purpose is to manage the complex financial lives of the families they serve. One key activity they perform is ensuring that the families’ bills are paid accurately, on time, and with appropriate oversight and safeguards.
Bill payment and related treasury functions often receive less attention than investment strategy, estate planning, philanthropy, or family governance. All too often, cash and expense management activities are under-resourced, rely on outmoded or point-solution technology, and can be prone to errors or worse.
Bill pay often gains executive attention only when something goes wrong, such as when the office receives a call from a family member about a missed or incorrect payment. This lack of focus, however, belies its importance. The downstream effects are real: missed or incorrect payments can impact a family member’s plans, trigger penalties, and damage credit relationships. Poor transaction oversight can expose a family member to fraud. The lack of coordination with a comprehensive treasury and accounting function can lead to overdrafts, duplicate payments, and late fees. Poor documentation hinders oversight and reporting and can complicate tax and audit preparation. Current approaches may lack scalability and redundancy and may not meet operational demands as family wealth structures grow more complex. As the number of entities grow and the volume and variety of invoices multiply, staff can quickly become overwhelmed.
This article examines the key challenges family offices face in managing bill payments and cash management, the risks created by inadequate processes and technology, and the principles and approaches that family offices need to adopt to modernize this important function.
Why Family Office Bill Pay Is So Complex
In most instances, family offices are managing payments for multiple entities in an ecosystem of fragmented financial interests and structures. A typical ultra-high-net-worth family may hold assets and require disbursements through a combination of the following:
- Personal residences and vacation properties in multiple states or countries
- Revocable and irrevocable trusts for estate planning purposes
- Family limited partnerships and limited liability companies
- Private foundations and donor-advised funds
- Operating businesses and holding companies
- Investment accounts and special purpose vehicles
The personal lifestyles of individual family members also generate a broad array of recurring and, at times, irregular payment obligations, including:
- Property management and related fees across multiple residences
- Household staff payroll, benefits, and employment taxes
- One-time or periodic purchases of luxury items: cars, aircraft, art, and yachts
- Luxury asset maintenance
- Personal security services
- Educational expenses
- Medical concierge services and ongoing healthcare
- Subscriptions, memberships, and club dues
- Family member-specific tax obligations
- Charitable pledges and recurring donations
- Capital call obligations for private fund investments
It is easy to see how quickly the payment environment can become complex as each payment category involves different vendors, payment frequencies, levels of urgency, approval processes, and sources of funds. Invoices must be paid for by the correct entity and from the correct bank account. Some family members or entities may have their own bank account, payment obligations, and accounting requirements. Others may simplify the process by paying invoices from one entity and allocating expenses across the partnership structure through the accounting process. All of this needs to be reconciled across multiple transactions, statements and recorded in the accounting system.
Complexity increases when families maintain residences, businesses, and service relationships across multiple jurisdictions. This can result in invoices in multiple currencies, international wire transfers, currency conversion, correspondent banking fees, and cross-border compliance requirements, adding another layer of complexity to the bill pay process.
Operational Challenges
Legacy family offices may rely on less formalized or consistently documented processes. Invoices arrive through multiple channels, often in hard copy, including paper mail, email, vendor portals, and property management systems. Invoices are often handled in hard copy with little tracking or workflow management. It is easy to make duplicate payments when invoices are received through multiple channels and processed independently. Misplaced invoices and missed payments can also arise when invoices fall through communication gaps or are simply lost.
Expense approval and oversight can be haphazard. Family offices typically maintain payment approval thresholds, with amounts below which staff can authorize payments independently and amounts above which principal or trustee approval is required. In practice, these frameworks are frequently informal and inconsistently applied, lacking approval documentation, tracking capabilities, and an audit trail.
Many family offices use spreadsheets, small business accounting software, or a combination of the two to manage their bill payment process. While flexible and familiar, spreadsheets present fundamental limitations for payment management, including:
- Poor spreadsheet access controls can allow any user with file access to alter payment data without an audit trail.
- The lack of version management can result in staff working from outdated files, creating conflicting records.
- There is little workflow to support the end-to-end process.
- Manual data entry can lead to errors.
- There is little system integration, with data manually entered into other recordkeeping and accounting systems, creating redundant work that is time-consuming and may diverge from the official books and records.
Many accounting platforms pose their own set of challenges. They are not designed for family office complexity and may lack integration among payment processing, cash reconciliation, and the general ledger. Workarounds that allow these platforms to approximate family office requirements can create duplicative processing and reconciliation of data between systems, increasing the risk of errors. In addition, they have significant reporting limitations that require manual effort to overcome.
Finally, a key challenge is the lack of staff redundancy. Family offices frequently have lean staffing models. Often, this complex process relies on a single employee or a handful of employees. If someone leaves or is unavailable, this can create a gap in the bill-paying process.
Coordination with Treasury Functions
Communication and coordination with treasury functions present another challenge. Once an invoice is approved for payment, the treasury function must be notified of the correct bank account and the amount of the payment. Treasury must then review relevant banking details to ensure adequate funds are available to meet the obligation. Treasury then notifies the bill pay team to execute the transaction. Without a robust workflow and platform, this process often relies on email and callbacks and is prone to errors.
Fraud Prevention Can Be Weak
Not surprisingly, family offices are potential targets for financial fraud. The combination of substantial assets, lean staffing, informal processes, and lack of systemic controls can create an environment that sophisticated fraudsters can easily exploit.
One approach is known as a Business Email Compromise (BEC) attack. Fraudsters compromise or spoof the email account of a trusted party — a property manager, investment manager, attorney, or one of the principals themselves — and issue fraudulent invoices or payment instructions to family office staff.
A vendor impersonation scheme is another fraudster favorite. A fraudster monitors family office communications and business relationships to learn of important vendor relationships. In a typical vendor impersonation scheme, attackers send invoices using spoofed or lookalike domains that closely resemble legitimate vendors, request bank account changes for future payments, and exploit informal vendor management practices that lack verification protocols. Without fraud detection and prevention processes, it is easy for busy staff to miss fraudulent activity.
Family offices are also not immune from internal fraud. They often operate with insufficient segregation of duties in their payment functions. A single employee may have authority to add new vendors, initiate payments, and reconcile bank accounts — three functions that should ideally be performed by separate individuals to create appropriate segregation of duties and oversight.
New Solutions and Best Practices
Leading family offices are addressing these challenges by taking a fresh approach to bill pay and the broader cash and expense management process. Through a combination of technology, organizational design, workflow tools, process discipline, and outsourcing to a third party, they are adding significant scale, efficiency, and safeguards.
Purpose-built family office bill payment platforms can now provide capabilities specifically designed for the multi-entity, multi-bank, multi-currency environment. These platforms consolidate and digitize invoice receipt and capture and allow for invoice tracking and multi-tier approvals with complete audit trails. They enable payment execution across multiple payment entities, automatic reconciliation with accounting systems, and consolidated reporting across all entities. Also included are important aspects of the treasury function to ensure funds are available to meet obligations and payments are made from the correct accounts. By outsourcing this function, a family office can gain access to a best-of-class technology platform and achieve scalability and personnel redundancy.
Key Components of a Modern Bill Pay Workflow
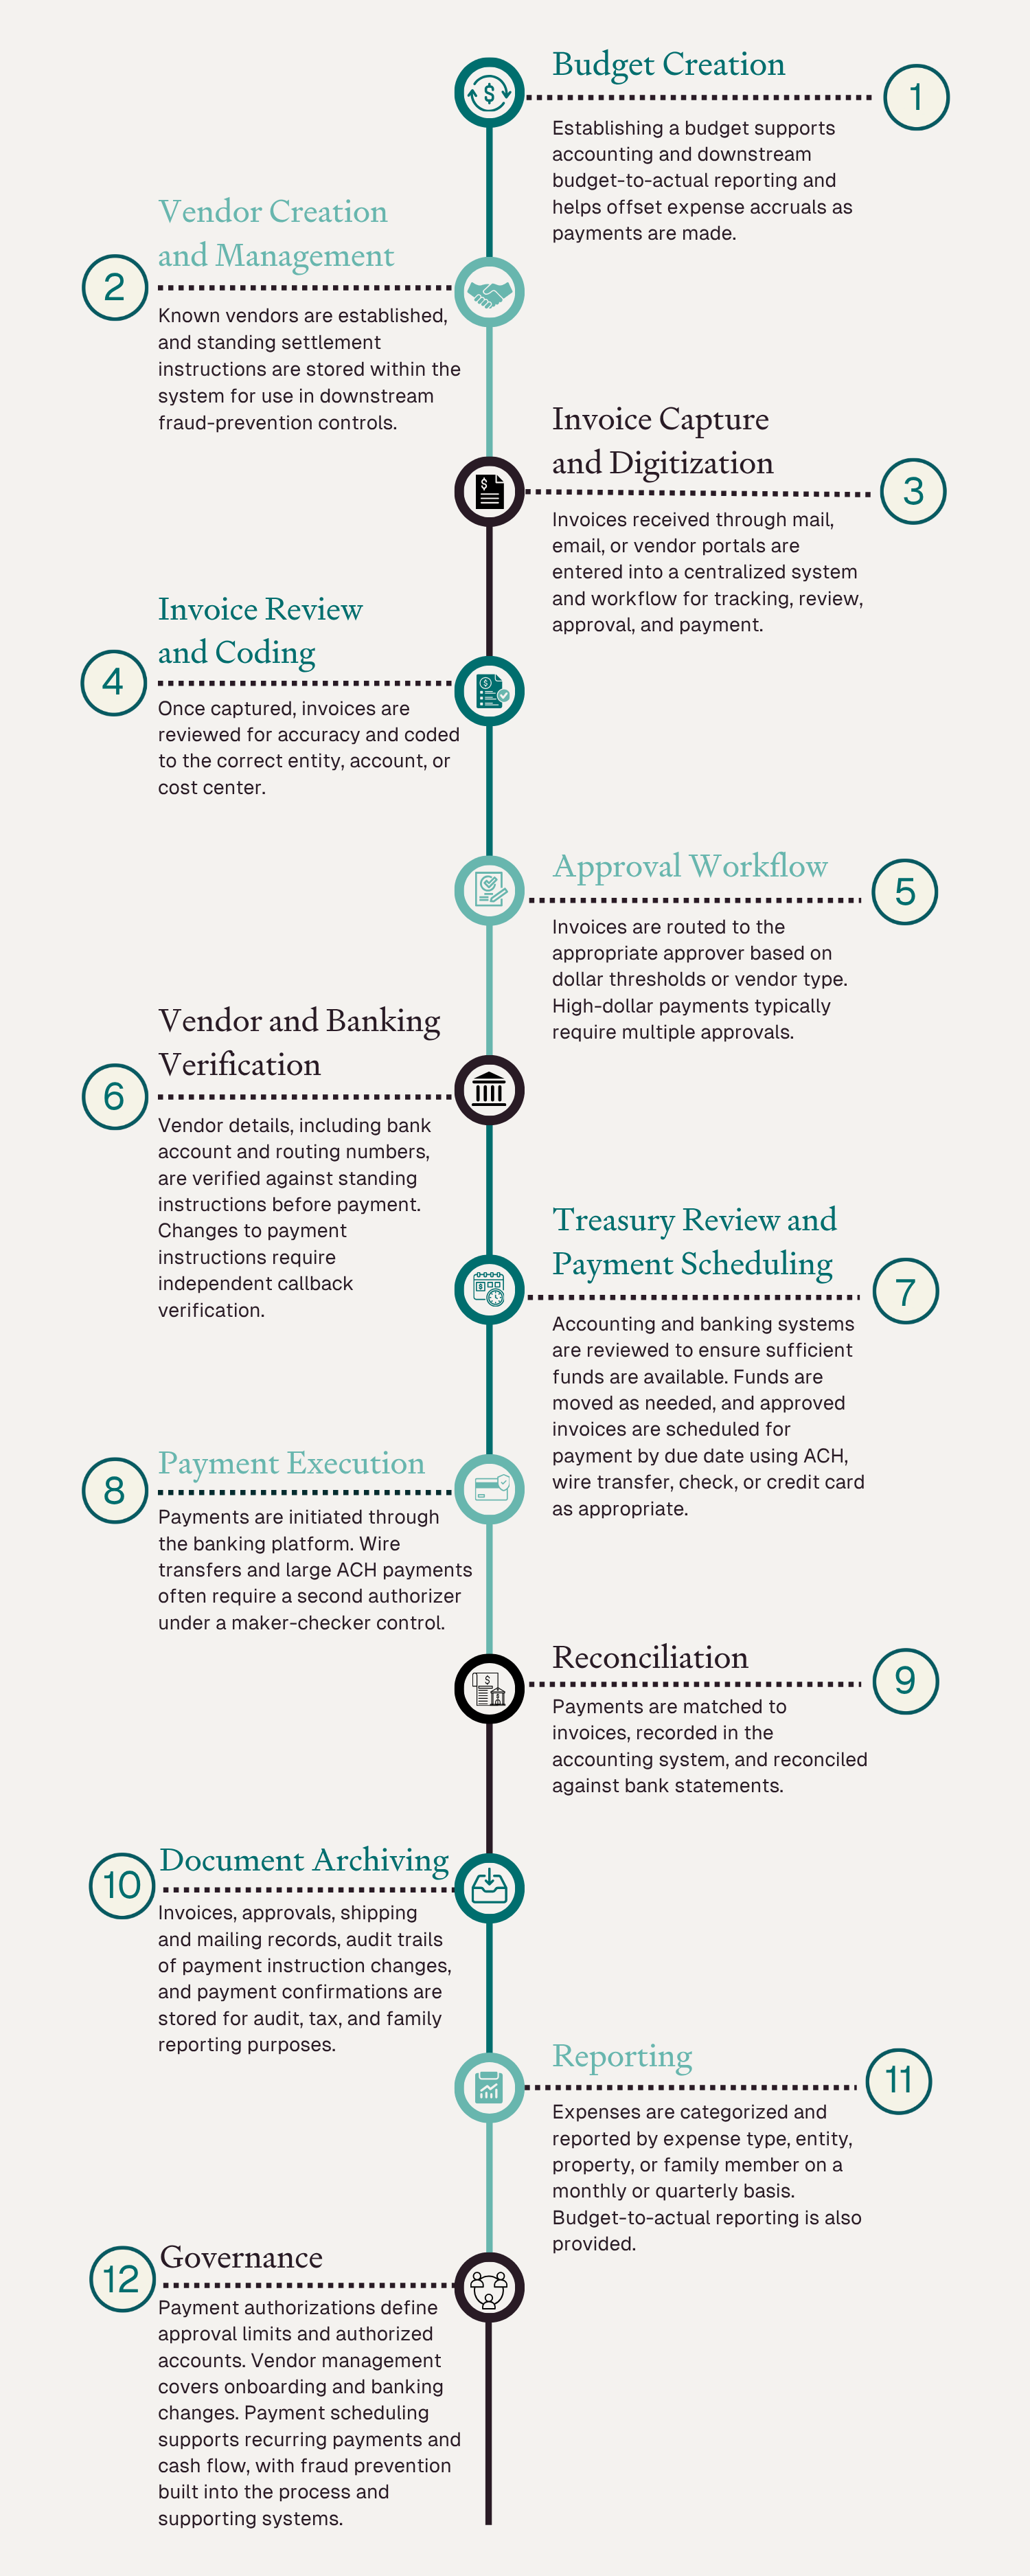
Whether managed internally or with an outsourced partner, a modern family office bill pay workflow should include the following components.
.png)
How Archway Can Help
Bill payment management sits at an unusual intersection in the family office: it is operationally essential yet often organizationally undervalued, technically complex yet frequently entrusted to informal processes, and financially significant yet rarely properly resourced.
Archway’s Cash and Expense Management solution addresses the treasury, accounting, and bill pay needs of complex family offices. Our secure, permission-based platform manages the full operational lifecycle of the payment process, from invoice receipt and approval through payment generation, reconciliation, general ledger integration, and reporting. Clients can delegate the full process to the Archway team or retain control over selected activities, including approvals and fund disbursements.
Recognizing the value of an enterprise-grade treasury and accounts payable platform can achieve more timely bill payment, better cash management, more accurate reporting, stronger fraud detection, and a more efficient payment process.


Article
·
Single Family Offices
·
time
-min
read
5 Signs Your Family Office Has Outgrown Spreadsheets
Spreadsheet dependency often develops gradually, creating hidden costs through manual workflows, fragmented data, and increasingly complex reporting processes. As family offices grow, a centralized financial foundation becomes essential for improving visibility, reducing operational risk, and supporting long-term scalability.

Richard Griffith
The Hidden Costs of Spreadsheet-Driven Family Office Operations
Most family offices do not wake up one morning and decide to build a spreadsheet-driven operating model.
It happens gradually.
A spreadsheet created to solve one reporting challenge becomes two, then ten. Over time, critical financial information becomes dispersed across workbooks, shared drives, email attachments, and manual processes. What began as a practical solution transformed into operational dependency.
For many organizations, that dependency develops quietly. Reporting continues to be delivered. Financial statements are produced. Capital activity is tracked. Ownership schedules are maintained. The process may not appear broken, but the effort required to sustain it increases with every new entity, investment, account, and stakeholder added to the environment.
The issue is not Excel itself. Spreadsheets remain one of the most valuable tools available to finance professionals. The challenge emerges when spreadsheets evolve from analytical tools into systems of record that support critical family office accounting, reporting, and operational processes.
As family offices grow more complex, the hidden costs of spreadsheet-driven operations become increasingly difficult to ignore.
Why Spreadsheet Dependency Persists
For many family offices, spreadsheets offer speed, flexibility, and familiarity—enabling quick reporting and custom analysis without relying on technology resources. That flexibility is valuable, but it also drives deep reliance on spreadsheets in daily operations.
Over time, they become the default solution for increasingly complex needs: investment data in one workbook, ownership in another, capital accounts elsewhere, and reporting assembled manually. Individually manageable, these processes collectively create an operating environment that is difficult to scale, govern, and sustain.
Where the Real Effort Is Hidden
When finance and operations teams evaluate their reporting processes, they typically focus on whether reports are ultimately delivered accurately and on time. While those outcomes matter, they do not always reveal the amount of effort required to achieve them.
Many family offices spend significant time collecting information from custodians, investment managers, banks, accounting systems, fund administrators, and third-party providers before reporting can even begin. Data must be validated, reconciled, reformatted, consolidated, and reviewed. Adjustments are made manually, and supporting schedules are frequently maintained outside core systems.
This work is often treated as a normal part of the reporting cycle because it has existed for years. But the true cost is the cumulative burden created by hundreds of manual activities across every close, every reporting cycle, every capital activity update, and every year-end process.
When Complexity Outgrows the Spreadsheet
Family office environments present operational challenges that differ significantly from those of mature businesses with enterprise-scale finance organizations.
Many organizations manage multiple legal entities, trusts, partnerships, foundations, operating companies, investment vehicles, and family ownership structures simultaneously. Reporting requires information to be consolidated across operating entities, investment entities, trusts, partnerships, and beneficiaries. Capital account reporting, partnership allocations, intercompany activity, trust distributions, and investment reporting all introduce layers of complexity that are difficult to manage when information resides across disconnected spreadsheets.
As complexity grows, spreadsheets become increasingly difficult to maintain. A change to an ownership structure may require updates across multiple workbooks. A new investment may introduce additional reporting requirements. Partnership allocations must be calculated, validated, and reflected consistently across capital accounts. Intercompany transactions must be reconciled. Custodian data must be normalized before it can be used in consolidated reporting for family offices.
Even straightforward reporting requests will require substantial manual effort when accounting data, investment data, ownership records, and supporting schedules are maintained across different files and systems.
Several warning signs often emerge.
- Reporting Cycles Become Longer
Finance teams spend more time gathering and validating information before analysis and reporting can begin. Month-end, quarter-end, and year-end processes become increasingly dependent on manual coordination, especially when reporting packages require data from multiple custodians, investment managers, entities, and accounting schedules.
- Reconciliations Become More Difficult
Multiple versions of the same information begin to exist across different files and teams. Custodian data may not match accounting records. Investment manager statements may need to be reconciled against internal books. LP capital account balances may require manual validation before year-end reporting or K-1 production can move forward.
- Knowledge Becomes Concentrated
Critical reporting processes become dependent on a small number of individuals who understand how spreadsheets were built, linked, and maintained. If a controller, accountant, or operations lead leaves, the family office may lose the institutional knowledge behind how key reporting, allocation, and reconciliation processes actually work.
- Visibility Declines
As information becomes fragmented across systems and files, it becomes more difficult to obtain a complete view of financial activity across the organization. Leadership may struggle to quickly understand liquidity positions, entity-level exposures, ownership relationships, and overall portfolio performance without waiting for manual consolidation.
- Growth Creates Additional Strain
What worked effectively for ten entities may not work for fifty. What worked for a handful of investments may not work for hundreds. As entities, accounts, partnerships, and reporting stakeholders increase, the effort required to sustain spreadsheet-driven processes often grows faster than the team supporting them.
These challenges create operational and investment risk. They also affect confidence.
Why This Matters More Than Ever
Family offices have the volume, complexity, and pace of information more akin to large and mature business yet maintain lean staffing more like a small business.
Many entities have significant or complex accounting and accounts payable needs. Investment portfolios are more diversified. Reporting expectations continue to rise. Stakeholders expect faster access to information and greater transparency across assets, entities, and ownership structures. At the same time, many family offices are being asked to do more with lean teams and finite resources.
Many organizations are also exploring automation, advanced reporting capabilities, and artificial intelligence to improve efficiency and decision-making. These initiatives have real potential, but they depend on one common prerequisite: reliable data.
Organizations cannot automate inconsistent processes. They cannot generate meaningful insights from fragmented information. They cannot fully benefit from AI if the underlying data lack’s structure, consistency, and governance.
Technology can accelerate existing processes, but it cannot compensate for poor data quality.
Excel Still Has an Important Role
None of this suggests that family offices should eliminate spreadsheets.
Excel remains one of the most effective tools available for financial analysis, forecasting, budgeting, modeling, and scenario planning. It provides flexibility that many systems cannot replicate.
The objective is not to remove spreadsheets from the finance function. The objective is to ensure that spreadsheets support analysis rather than serve as the primary repository for critical operational and financial information.
Organizations that establish this distinction are often better positioned to improve family office reporting, strengthen controls, reduce operational risk, and support future growth.
How Archway Can Help
Archway helps family offices bring accounting, investment data, and reporting together within a single platform.
With support for multi-entity accounting, complex ownership structures, capital account accounting, consolidated reporting, and family office-specific workflows, Archway helps reduce manual effort while improving visibility, consistency, auditability, and control.
That matters in the areas where spreadsheet dependency creates the most strain: ownership allocations, entity-level reporting, intercompany reconciliation, capital account tracking, and the ability to trace numbers back to the source.
For organizations seeking additional support, Archway’s Family Office Accounting services can help with bookkeeping, accounting, investment reporting, and related operational workflows.
The result is a stronger foundation for reporting, governance, scalability, and long-term growth.
Looking Ahead
Spreadsheet dependency is often a symptom of growth. As family offices become more sophisticated, the operating practices that once supported the organization may become increasingly difficult to sustain.
The next step is not simply replacing spreadsheets. It is creating a stronger foundation for financial data, reporting, governance, and decision-making.
In the next article, we explore what that foundation looks like and why it has become increasingly important as family offices prepare for a future shaped by automation, advanced reporting, and artificial intelligence.


Article
·
Single Family Offices
·
time
-min
read
Strategic Partnership Highlight: Archway's Platform℠ x Canoe Intelligence
Highlights Archway and Canoe Intelligence’s integration for alternative investment data, including automated fund data extraction, pricing updates, and capital call workflows.
Archway Family Office Services
Archway and Canoe Forge Path to Further Advance Alts Data Management for Family Offices Using the Archway Platform
Since 2020, collaboration and a desire to solve complex financial problems have been at the core of Archway and Canoe Intelligence’s strategic partnership. Throughout the years, Archway’s experience working with nearly 600 ultra-high-net-worth families through the Archway Platform has made them acutely familiar with the challenges family offices face when it comes to collecting and reporting on alternative investment data.
Coupled with Canoe’s innovation and vision in the alts technology space, where the Canoe platform covers 42,000 active funds across $8T in Assets Under Management or Advisement for its 325 alternative investor clients, our teams knew early on there was an immense opportunity to streamline alternative investment data management within the family office space.
Recently, the two teams have been working on the next iteration of our partnership as we develop a more robust integration between the Canoe and Archway platforms.
This integration between Canoe and Archway automates the transmission of private equity and hedge fund valuations, as well as Private Equity Call and Distribution data. Moreover, Hedge Fund subscriptions and redemptions extracted from Canoe can be effortlessly imported into Archway.
In this article, we share how the two technologies are teaming up to test and build this expanded integration—and how we believe it can level up the operational efficiency for our mutual family office clients.
Common Challenges in Alts Data Management
Alternative investors, particularly family offices, navigate a complex landscape fraught with challenges when it comes to managing alts data. Among these challenges are data silos, where crucial information is scattered across multiple systems and platforms, making it difficult to obtain a comprehensive view of investments. Additionally, the reliance on manual data entry introduces a significant risk of human error and inefficiency, consuming valuable time and resources.
Compounding these issues is the lack of standardized data formats, further complicating the integration and analysis of disparate data sources.
In response to these challenges, Archway Family Office Services and Canoe Intelligence are expanding their strategic partnership and integration methods. By automating data transmission and ensuring data consistency, the integration streamlines the process of accessing and integrating alts data. This not only enhances operational efficiency but also mitigates the risk of errors, empowering family offices to make informed decisions with confidence.
How Canoe Enhances Archway’s Platform
- Automated Fund and Allocation-Level Data Extraction: Canoe's integration with the Archway Platform facilitates automated extraction, validation, and delivery of fund and allocation-level data.
- Pricing Updates: Canoe seamlessly updates pricing information in Archway, providing alternative investment valuation data extracted as soon as received and processed.
- Effortless Management of Capital Calls and Distributions: Canoe automates the process of updating Archway with capital call and distribution transactions.
- Streamlined Subscription and Redemption Transactions: Canoe generates extracts of subscription or redemption transactions, which can be uploaded directly to Archway.
Archway’s Platform at a Glance
Archway's Platform serves as a comprehensive wealth management technology solution tailored specifically for family offices. With Archway, family offices gain access to a wide range of benefits, including a 360-degree view of clients' wealth, enhanced operational efficiency, improved data accuracy and reliability, and robust operational and client reporting.
Bringing the Integration to Life
Prior to launching beta testing for the integration in late 2023, the Archway and Canoe teams worked in concert to automate data flows, normalize values, and define accounting rules and transaction mapping across systems.
The teams collaborated on extensive internal testing to validate the effectiveness and reliability of the integration, with the intent to not only automate the transmission of alternative asset data between platforms, but to simplify the complex nature of accounting for alternative investment transactions.
Through rigorous analysis and learning, the team identified and addressed potential challenges, fine-tuning the integration to meet the unique needs and requirements of family offices.
Now in its beta testing phase, the team continues to collect invaluable real-world perspectives, helping to guide iterative improvements and ensuring alignment with client expectations.
To date, Canoe has processed 150,000+ documents on behalf of Archway’s clients. Additionally, this collaborative effort has positioned two dozen mutual clients to automate the transmission of data across 3,400+ alternative investments, underscoring the substantial impact of the integration on operational efficiency and data management accuracy.
What's Coming Next
Looking ahead, Archway and Canoe are finalizing the initial integration offering with plans to expand the universe of data available to mutual clients seeking to automate the transmission of their alternative asset data. This next phase promises to unlock new levels of efficiency and value for family offices leveraging the combined power of the Archway’s Platform and Canoe Intelligence.
As Archway continues to leverage Canoe's capabilities, clients can expect further enhancements that drive continued scale and elevate client satisfaction. With a commitment to innovation and excellence, Archway and Canoe are poised to shape the future of alts data management. Stay tuned for more updates as the integration nears launch later this year.
Disclaimer: All statistics as of March 31, 2024.
Originally published by Canoe Intelligence.